
Alphabet: Search Is Fine. The $200 Billion AI Bill Is the Question.
Google's business is strong. The stock just isn't cheap while it spends this much on AI.
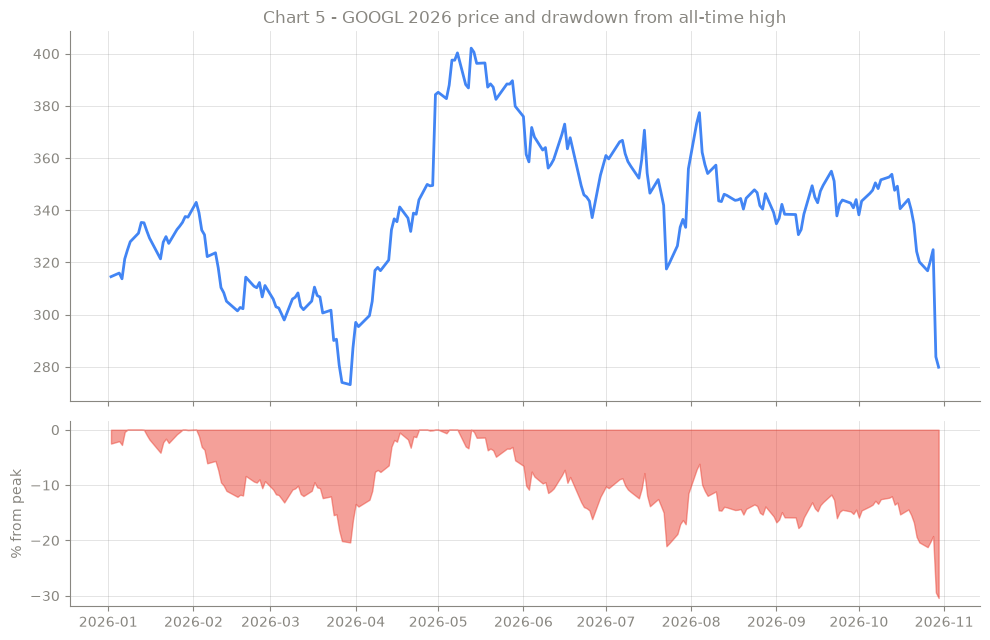
Alphabet stock is down 30% from its $402 high in May, and October was its worst month ever. Many investors fear AI chatbots will kill Google Search. We looked at the numbers to answer one question: is Alphabet a bargain, or a business in trouble?
Short answer: neither. Search is fine, but Google is spending so much on AI that the stock isn't cheap. Here are five things the headlines miss.
1. Search is still growing
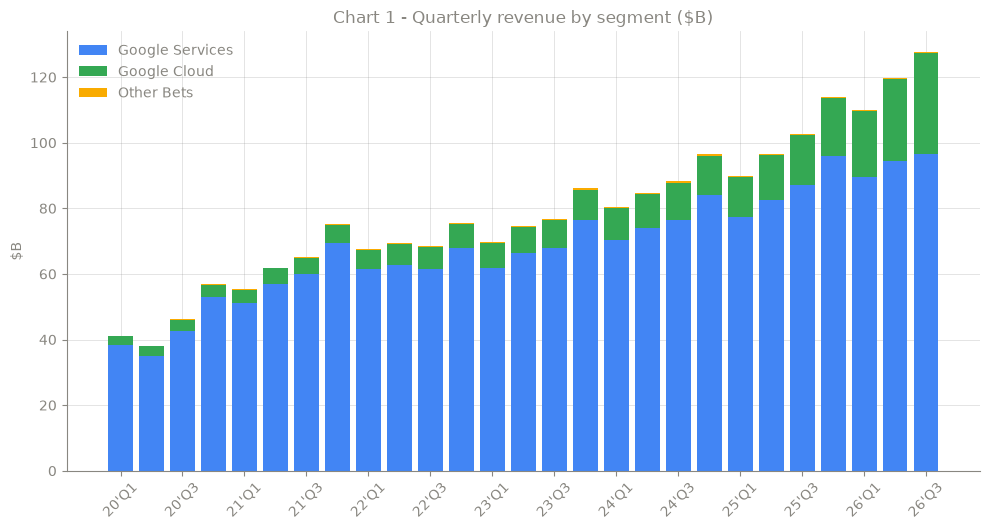
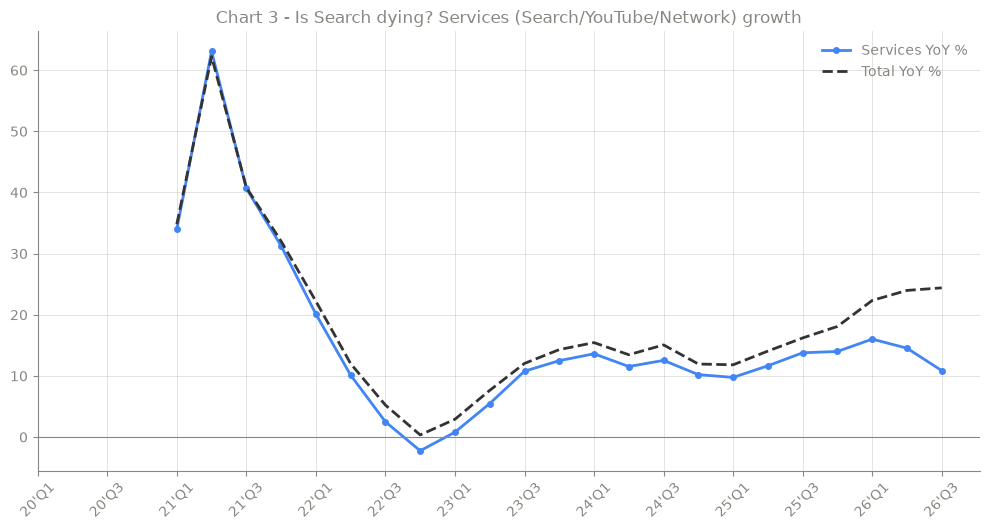
Search revenue grew 12% last quarter. Search, YouTube and ads bring in about $96B a quarter and pay for everything else. Growth is slowing, but AI hasn't hurt it yet.
In fact, Google says people are searching more than at any time in the past five years, and searches in its AI Mode are three times longer than regular ones. The open question is pricing: Google doesn't share how much advertisers pay per click on AI answers, and that is the number to watch.
2. Cloud is the growth engine
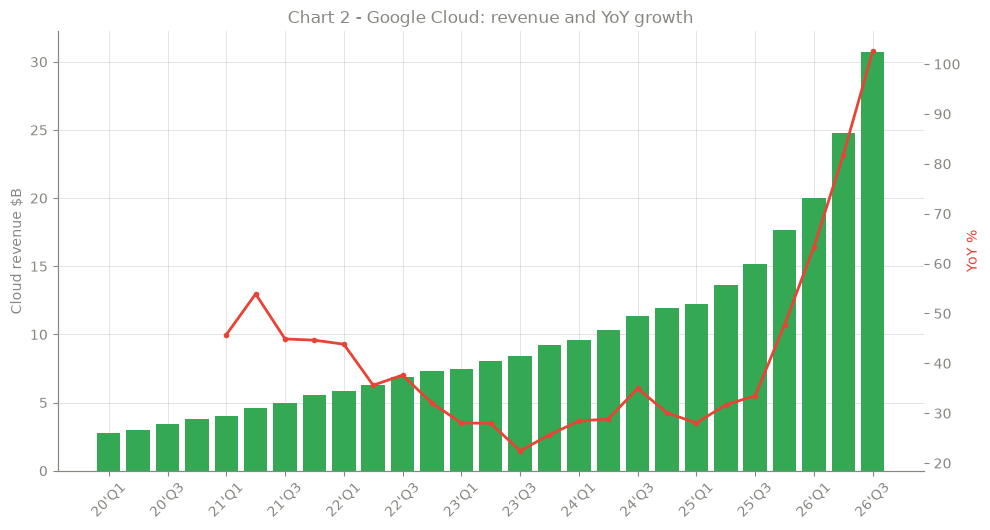
Cloud revenue doubled to $30.7B, beating Azure (48%) and AWS (39%). Google also has $561B in signed Cloud contracts, much of it from selling its own AI chips.
Google expects just over half of those contracts to turn into revenue within two years, so much of the next leg of growth is already signed. Its AI chips, called TPUs, now have nearly 100 customers, including Anthropic and Apple, and the Gemini app has passed 1 billion users. Few companies own the whole AI stack like this: the model, the chips, the cloud and the users.
3. The stock only looks cheap
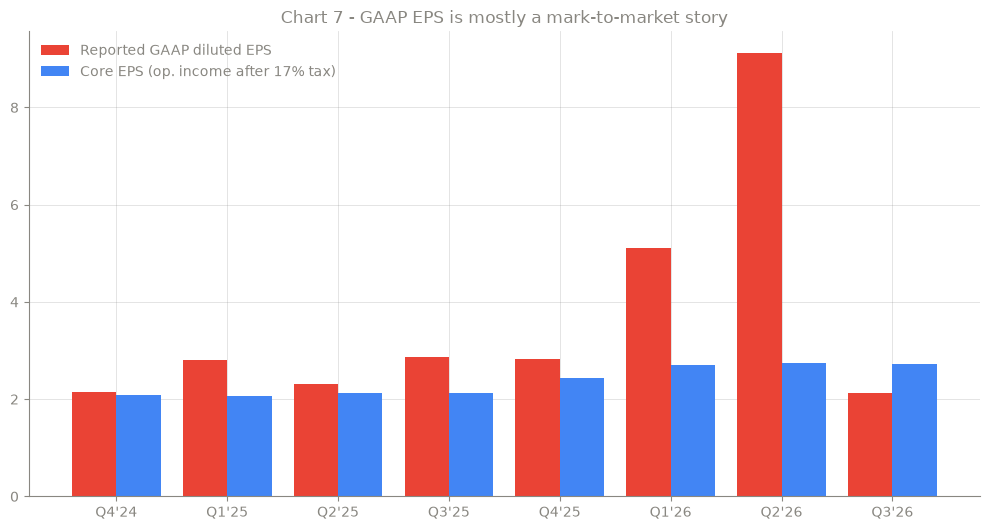
The 14.6x P/E is boosted by about $127B of one-off gains, mostly from the SpaceX IPO. Without them, Alphabet trades at about 26x earnings, the same as Microsoft.
You can see it in Q2: reported earnings were $9.11 a share, but the core business earned closer to $2.75. Those gains can also reverse. In Q3 the same investments lost $8.7B, which helped push reported earnings below expectations.
4. AI spending is eating the cash
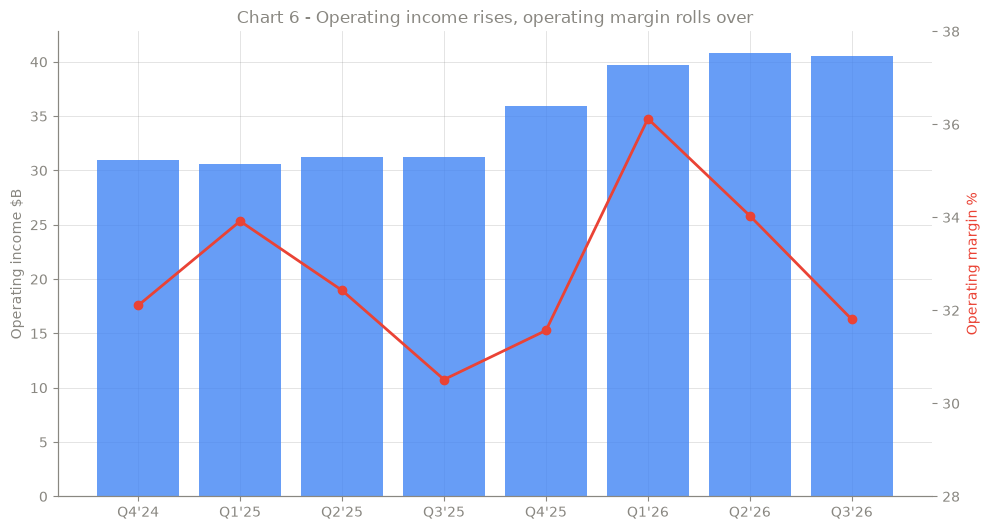
Last quarter Google spent $51.4B on data centers, more than its $40.6B operating profit. Profit margins fell from 36% to 32% this year, and stock buybacks have stopped.
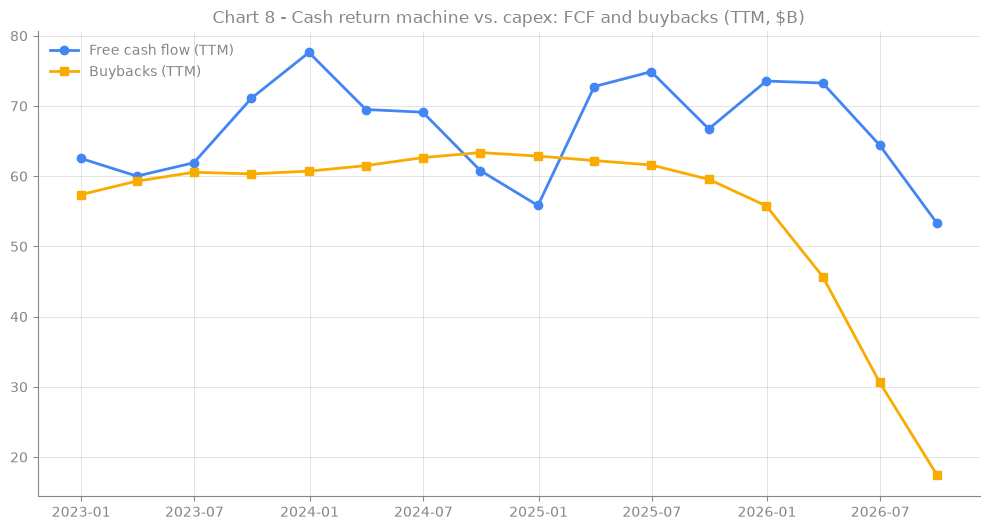
That spending is more than double the $24B of a year ago, and Google plans about $200B for all of 2026, with more coming in 2027. Buybacks have dropped from $63B a year to $17B. For years, investors counted on Google handing back cash. For now, that cash is going into AI.
5. The price already expects a lot
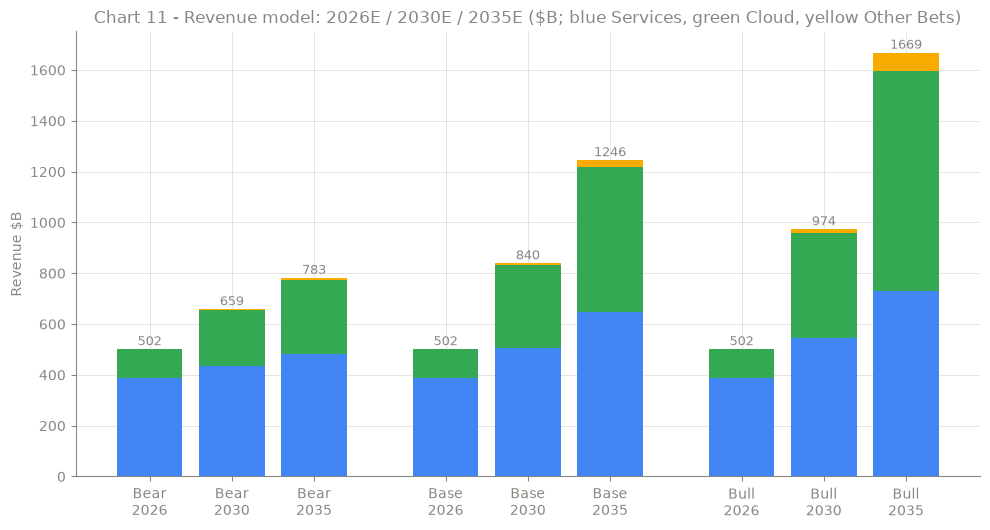
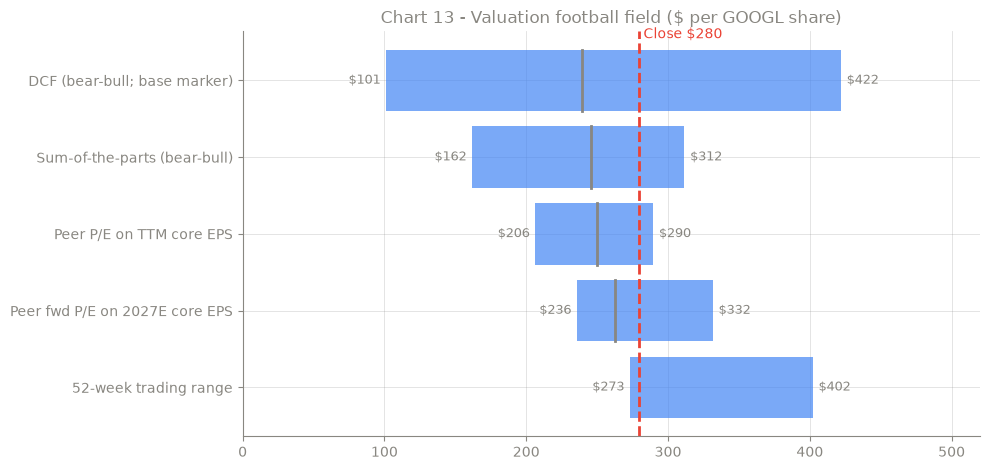
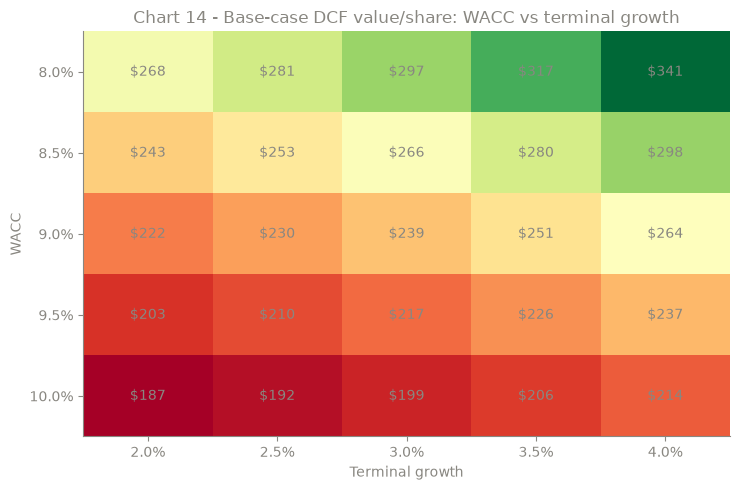
To be worth $280, Cloud must grow about 43% a year until 2030. We expect closer to 30%, which puts fair value around $249. Most methods land below today's price.
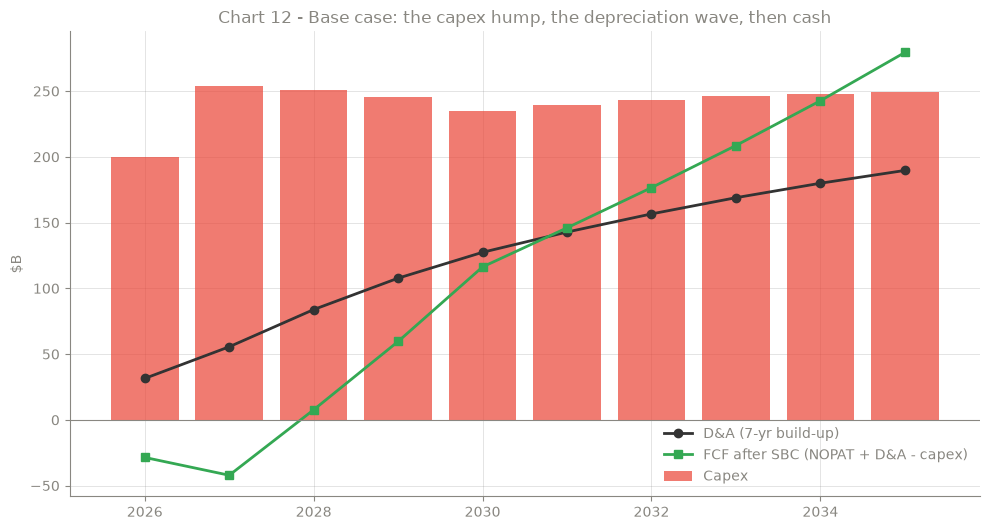
The range is wide because most of Alphabet's value depends on profits many years out, so small changes in assumptions move the answer a lot. In our base case, heavy spending keeps cash flow negative through 2027, and it turns positive in 2028 as Cloud revenue catches up.
| Method | Bad case | Expected | Good case |
| Cash flow model | $101 | $239 | $422 |
| Value of each business | $162 | $246 | $312 |
| Compared with peers | $206 | $256 | $290 |
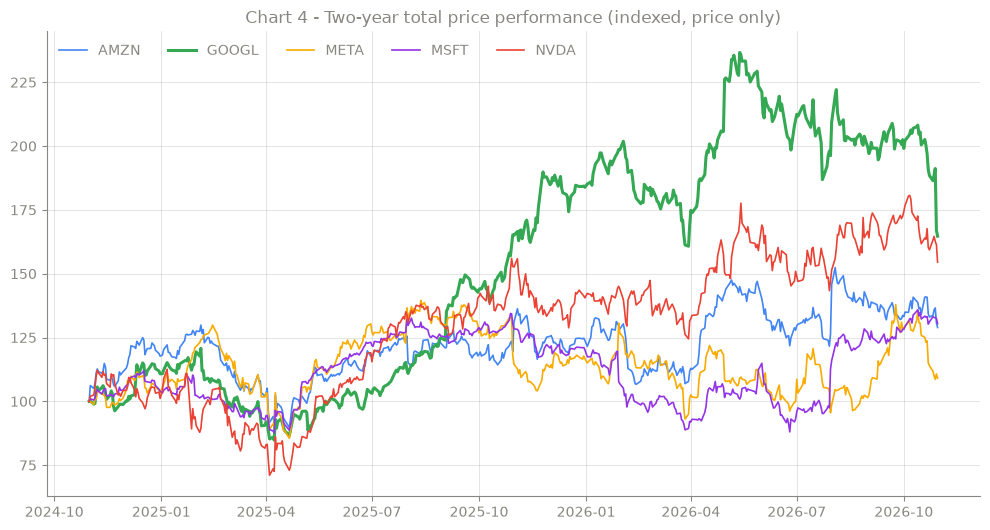
How Alphabet compares with peers. Google is growing faster than Microsoft and Amazon, but only Microsoft and NVIDIA are still producing positive cash flow while they build out AI.
| Company | Sales growth | Profit margin | Last-quarter cash flow |
| GOOGL | 25% | 35% | –$9.1B |
| MSFT | 19% | 46% | +$18.6B |
| AMZN | 12% | 12% | –$34.8B |
| META | 26% | 38% | –$1.2B |
| NVDA | 106% | 66% | +$21.4B |
The big picture: Alphabet is making one of the largest bets in business history. Search is funding it, and Cloud is starting to show it can pay off. What decides the next few years is how quickly that spending turns back into cash.
- What could go right: Cloud contracts turn into cash and chip sales keep growing.
- What could go wrong: Spending rises "significantly" in 2027, and Search growth slows further.
- What to watch: 2027 spending plans, buybacks restarting, Cloud margins and Search ad pricing.
Notes: Projections are ours. Waymo ownership and some segment figures are estimates. Private stakes like Anthropic aren't included in the value. This is research, not investment advice.
Sigmo can make mistakes — verify important info. Not financial advice.
Get AlphaWeekly in your inbox
Free. New issues as they are published, with the charts and the method in view.